Equity release
Part of the Life Well Spent Report 2026
Equity release can make life-changing spends possible, such as dream holidays, renovations, gifts to family, or paying off debts. But many still don’t know the ins and outs of equity release today.
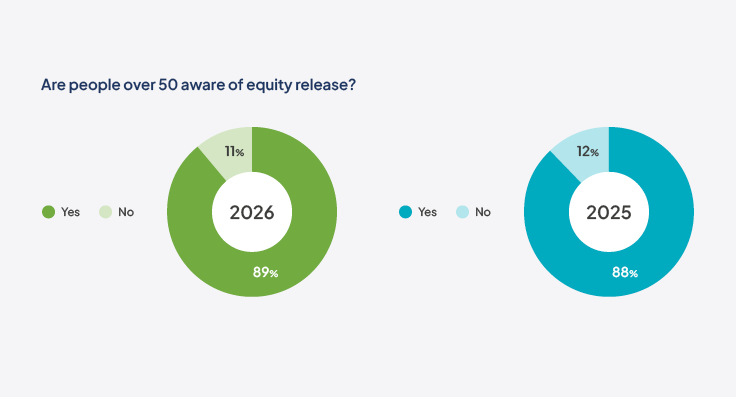
Just under 4 in 5 are aware of equity release
Equity release is a way to get tax-free cash from the value that’s tied up in your house. The most common type of equity release, a lifetime mortgage, is a loan that’s secured against your home. This is repaid when you die or move into permanent care.
Releasing equity could enable you to pay off debt, undertake home improvements, take that dream holiday or give your loved ones an early inheritance – plus much more.
78% of people over 50 are aware of equity release – 2% less than last year. Awareness rises to 88% among retirees, but this is also 1% less than in 2025. However, almost 9 in 10 (89%) of homeowners over 50 are aware of equity release, 1% more than 2025.
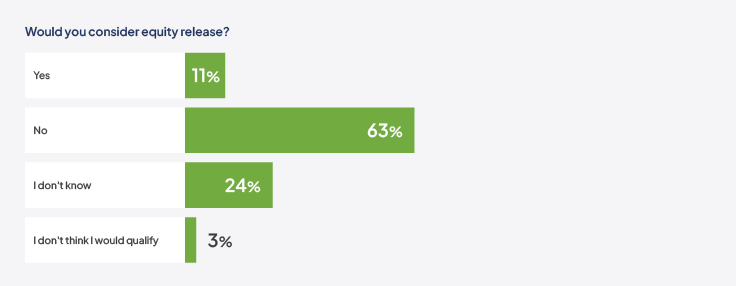
7% of eligible* homeowners have taken out equity release – representing under 4% of all people over 50. But of those who haven’t released equity, only 11% would consider it (-2%).
*Homeowners aged 55+ who are aware of equity release.
Only 7% know all the facts about equity release
Despite most people over 50 being aware of equity release, many are unaware of the ins and outs. And, like last year, awareness of many features has gone down, with 7% of homeowners who haven’t taken out equity release knowing nothing about it at all.
For example, just 44% of people over 50 know that equity release requires financial advice before you purchase it, down from 55% last year. Interestingly, the percentage of homeowners who know nothing about equity release - 7% - is the same as the percentage of homeowners who knew all the facts about equity release – although this percentage who know nothing is 1% higher than last year.
The least known fact is that some equity release plans can include ‘inheritance protection’ to ensure there will be money left for your family once the loan has been repaid. Only 23% of homeowners who are aware of equity release know this, down from 26% last year.
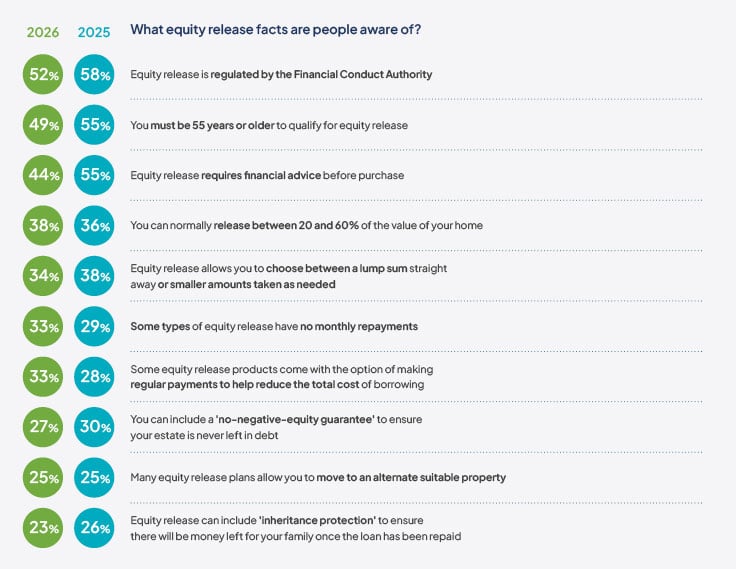
73% don’t know that equity release products that follow Equity Release Council standards have a no negative equity guarantee. This means homeowners releasing equity will never owe more than their home is worth, so their loved ones can’t be left in debt from equity release.
Those who wouldn’t consider equity release cite being wary about debt and wanting to give their family the full benefit of selling the home.
It’s worth keeping in mind that all types of equity release products will reduce the value of an estate and could affect eligibility for means-tested benefits. Anybody considering equity release should discuss their options with an expert adviser.
People would like to release about £78,000 of equity
On average, homeowners over 50 considering equity release would like to release £78,650. That’s £2,441 less than last year, but £4,611 more than in 2022.
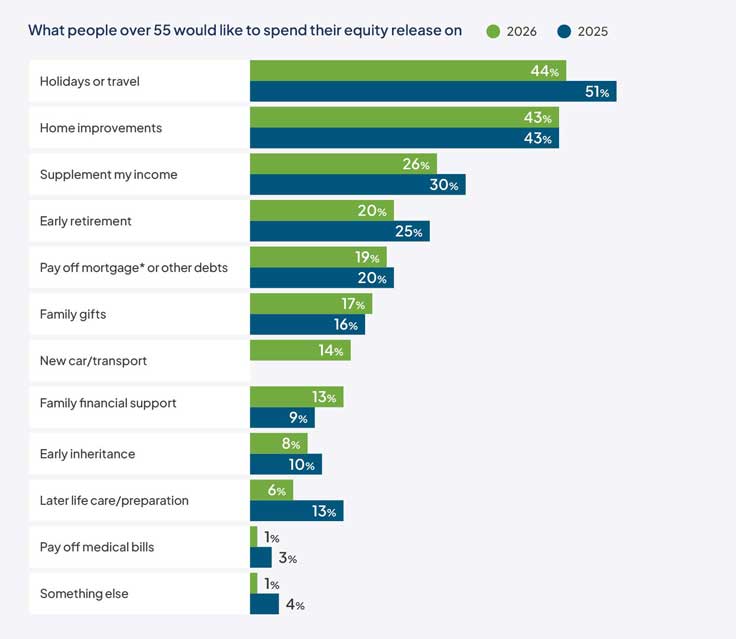
44% (down 7% since 2025) would spend at least some of the cash on holidays or travel. 43% would spend it on home improvements – the same as last year. 26% (-4%) would use it to supplement their income. Only 20% (-5%) would take an early retirement.
The amount of equity release people would spend on holidays has increased to £21,035 – up £462 since 2025 (but up by £3,790 since our first report in 2022).
The amount people would use to give their family financial support has also increased significantly from £23,715 in 2025, to £32,614 in 2026.
*Any equity released must first be used to pay off your remaining mortgage.
How much would people like to spend, and on what?
The amount people say they’d spend on giving their loved ones an early inheritance has risen slightly, from £33,000 to £37,377.
Supplementing income is back at the top spot in 2026, with people saying they would spend £58,945 on this (£6,922 more than 2025). Early retirement is now second at £51,595 (down by £9,419) and £7,218 down since 2022.
This is followed by later life care/preparation, at £41,835, which is £6,097 less than 2025.
If people released equity, what’s the average amount they’d spend on each of these?
| Average Expected Spend | 2026 | % of who would spend on this (2026) | 2025 |
|
Supplement my income* |
£58,945 | 26% | £52,023 |
| Early retirement* | £51,595 | 20% | £61,014 |
| Later life care/preparation* | £41,835 | 6% | £47,932 |
| Early inheritance* | £37,377 | 8% | £33,000 |
|
Family financial support* |
£32,614 | 13% | £23,715 |
| New car/transport* | £32,272 | 14% | £16,183 |
| Pay off mortgage or other debts* | £30,514 | 19% | £28,655 |
| Home improvements | £22,693 | 43% | £21,713 |
| Holidays or travel | £21,035 | 44% | £20,573 |
| Family gifts* | £17,427 | 17% | £16,183 |
| Pay off medical bills* | - | 1% | £6,848 |
*Low base size
People release just over £68,000 of equity on average
Of those who take out equity release (4% of all people over 50), the priorities and amounts spent tend to be quite different from those who are considering it.
On average, they release £68,169 – around £10,500 less than those in the consideration stage would like to release.
£68,169
the average amount of equity released in 2026
£66,581
the average amount of equity released from 2024-2026
If we look at our combined data from the last three years, those who have released equity unlock £66,581 on average.
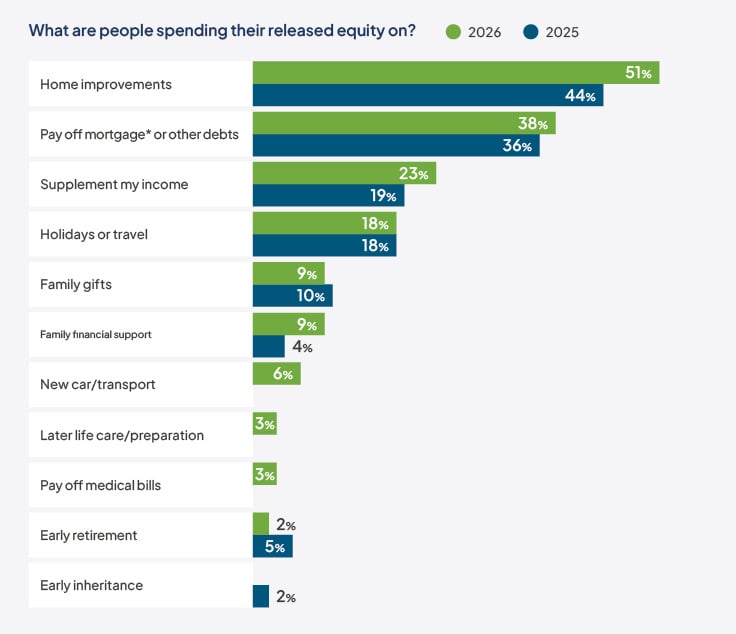
In 2026, home improvements are the most popular way to spend equity release, with 51% using the money for this purpose.
Second is paying off debts (including the mortgage, which is a requirement of all equity release schemes) at 38%. Third is supplementing income, at 23%. And fourth is holidays and travel, at 18%.
People spend most on paying off their mortgage and other debts
When we asked how much of their equity release cash was spent on each category, paying off the mortgage and other debts comes out on top, with an average spend of £36,139, an increase of £13,519 on last year. However, this is from a relatively low base size. When we combine the average spend on mortgage repayments over the past three years for a more robust figure, the average is much lower at £26,610.
Later life care preparation takes over supplementing income as the second highest spend, coming in at £15,500 - £500 more than 2025. Third is supplementing income at £15,376, a drop of £956. The average for family financial support was £9,893 and family gifts was £6,074.
Average equity release spend
| Average spend (2024-2026) |
Average spend (2023-2025) |
Average spend (2022-2024 ) |
|
| Pay off mortgage or other debts | £26,610 | £28,411 | £27,644 |
| Supplement my income | £17,471 | £18,332 | £12,706 |
| Family financial support | £15,013 | £17,540 | £17,212 |
| Home improvements | £13,310 | £12,361 | £11,188 |
| Early inheritance | £13,000 | £7,333 | £9,836 |
| Later life care preparation | £9,578 | £7,886 | £6,700 |
| Holidays or travel | £8,063 | £7,569 | £6,878 |
| New car/transport | £7,888 | - | - |
| Family gifts | £5,542 | £7,331 | £8,270 |
| Early retirement | £4,091 | £7,891 | £10,929 |
| Pay off medical bills | £2,000 | - | - |
* Due to low base size, these figures are a three-year combined average. I.e. the 2026 figure combines data from our 2026, 2025 and 2024 research.
Over two-thirds say equity release made them happier
At 70% (-6% since 2025), over two thirds of people who release equity say it’s made them happier, with 4 in 10 (42%) saying it’s made them significantly happier. 23% (+4% since 2025) say it’s had no impact on their happiness.
What motivates people to take out equity release?
Most people who take out equity release say they were motivated by wanting to pay off their traditional mortgage, make improvements to their home, or generally enjoy retirement more.
"To get rid of the mortgage as interest rates were starting to rise."
"Retire without worrying about income."
"There were refurbishments that needed doing, in order to make our home future-proofed."
"It made sense to have cash to use now as a lot of friends of the same age have died in the last 5-10 years."
"Wanted a holiday home."
"To give my children a desposit on a house."
If you’d like to know more about equity release, visit our Equity Release Hub.
Use our 60 second equity release calculator
See what your options might look like for releasing equity from your own home
This article forms part of our Life Well Spent report, which looks at the relationship between happiness and big purchases in later life.